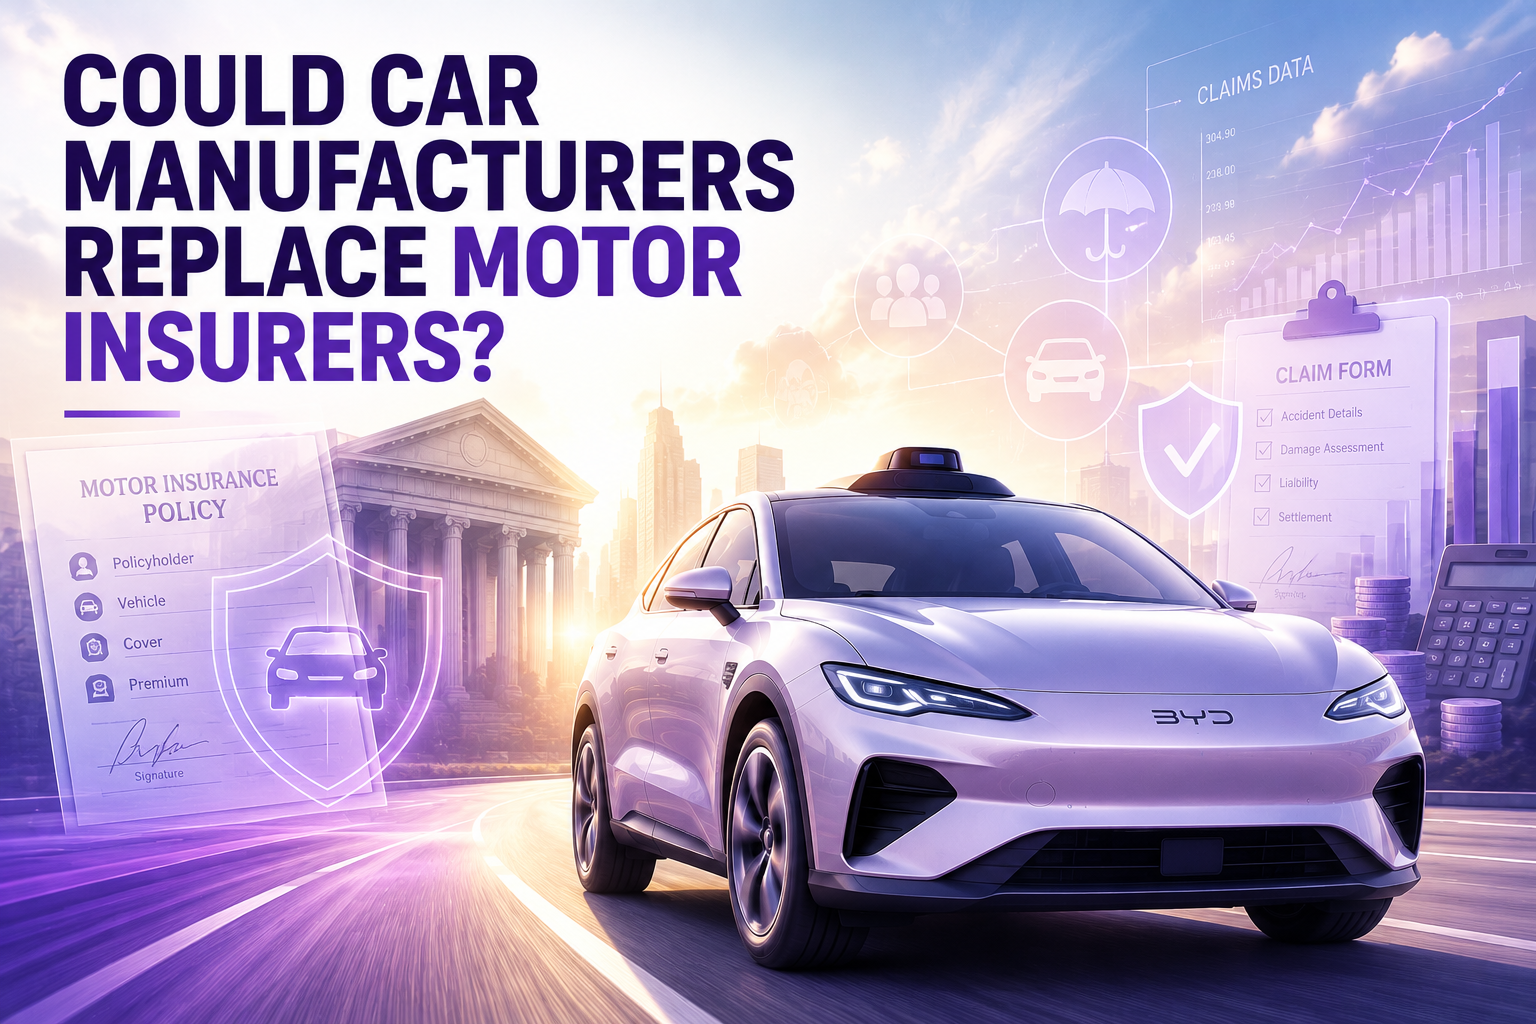
BYD's recent announcement may prove to be one of the most significant developments in motor insurance for decades. The Chinese automotive giant has stated that it will accept financial responsibility for accidents caused by its autonomous driving technology. In essence, if the vehicle is operating under approved autonomous control and the software is responsible for an accident, BYD will pay the resulting costs.
At first glance, this appears to be a straightforward customer confidence initiative. Manufacturers have long offered warranties and product guarantees, and accepting responsibility for software failures may seem like a natural extension of that approach. However, the implications for the insurance industry are potentially far more profound.
The announcement raises an important question: what happens when the vehicle manufacturer begins to assume the role traditionally occupied by the insurer?
For more than a century, motor insurance has been built around a simple principle. The primary source of risk is the person behind the wheel. Underwriters assess age, driving experience, claims history, occupation, postcode, vehicle type and a host of other factors designed to predict human behaviour. The better the perceived driver, the lower the premium. The higher the risk, the greater the cost of insurance.
Autonomous driving technology fundamentally challenges this model. As vehicles increasingly take responsibility for steering, braking, acceleration, hazard detection and route decisions, the source of risk begins to shift. Instead of underwriting human behaviour, insurers may find themselves underwriting software performance.
This is where BYD's announcement becomes particularly significant. Traditionally, if a vehicle defect caused an accident, the insurer would settle the claim and then potentially seek recovery from the manufacturer through subrogation. The insurer remained at the centre of the process and controlled the customer relationship. BYD's approach effectively reverses that position. Rather than waiting for insurers to pursue recovery, the manufacturer is stepping forward and assuming liability itself.
The distinction may appear subtle, but it has major implications. The manufacturer is no longer simply defending claims. It is accepting the financial risk that would ordinarily sit on an insurer's balance sheet.
This development becomes even more interesting when considering the unique position occupied by modern vehicle manufacturers. Companies such as BYD, Tesla and Mercedes-Benz now collect vast quantities of real-world driving data. Every journey generates information about driver behaviour, road conditions, system interventions, near misses, environmental factors and vehicle performance. In many cases, manufacturers possess significantly more detailed data about vehicle usage than insurers themselves.
Historically, insurers have enjoyed an informational advantage when pricing risk. In a world of autonomous vehicles, that advantage may begin to erode. Manufacturers increasingly control the vehicle, the software, the sensors, the repair network and the data generated by every mile travelled. They may eventually become better positioned to assess autonomous driving risk than traditional insurers.
If that happens, the possibility emerges that manufacturers could begin self-insuring certain categories of risk. For businesses producing millions of vehicles each year and holding substantial financial reserves, the economics could become increasingly attractive. Rather than purchasing large amounts of external insurance, manufacturers may decide to retain more risk internally and absorb losses directly.
The longer-term implications could be transformative. Today, motorists purchase a vehicle and then arrange insurance separately. In the future, vehicle ownership may become a fully integrated service. Finance, maintenance, software updates, connectivity, roadside assistance and liability protection could all be bundled into a single monthly subscription provided by the manufacturer. Consumers may no longer think of insurance as a separate product at all.
For traditional insurers, this presents a challenge that extends far beyond reduced accident frequency. Much of the discussion surrounding autonomous vehicles focuses on the possibility of fewer collisions and lower claims volumes. While that is undoubtedly important, the greater strategic threat may be disintermediation.
If manufacturers begin assuming responsibility for autonomous driving risks, insurers risk losing their position at the centre of the customer relationship. They may increasingly become providers of wholesale capital sitting behind manufacturer-backed schemes rather than the primary risk carrier recognised by the consumer.
That does not mean insurers disappear. The industry has repeatedly adapted to technological change and will undoubtedly continue to do so. However, the role of insurers may evolve significantly. Rather than pricing the behaviour of individual motorists, future underwriting models may focus on assessing the reliability of software systems, sensor packages, cybersecurity protections and autonomous driving platforms.
The UK is already moving in this direction. The Automated and Electric Vehicles Act established a framework recognising that liability may transfer from the driver to the automated driving system in certain circumstances. While the current legal framework still relies heavily on insurers, the legislation acknowledges a future in which responsibility increasingly shifts towards vehicle technology rather than human judgement.
BYD's announcement may therefore be viewed as an early indicator of a broader transition already underway. The motor insurance industry has spent decades refining its ability to assess human risk. The next challenge may be understanding and pricing the risk associated with millions of lines of code.
For insurers, brokers and the wider insurance market, the question is no longer whether autonomous vehicles will change the industry. The question is whether insurers remain the primary underwriters of road risk, or whether vehicle manufacturers gradually assume that role themselves.
For over a century, insurers have priced the risk of human drivers. The next century may be defined by manufacturers pricing the risk of their own technology.